How to Budget for a Home Renovation Step by Step
A step by step plan to budget for a home renovation, from setting a hard ceiling and contingency to tracking change orders so surprise bills never derail your project.
By Alexia Mabel
Learn more about Home Remodeling for guides, costs, and what to expect.
Compare Home Remodeling Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.
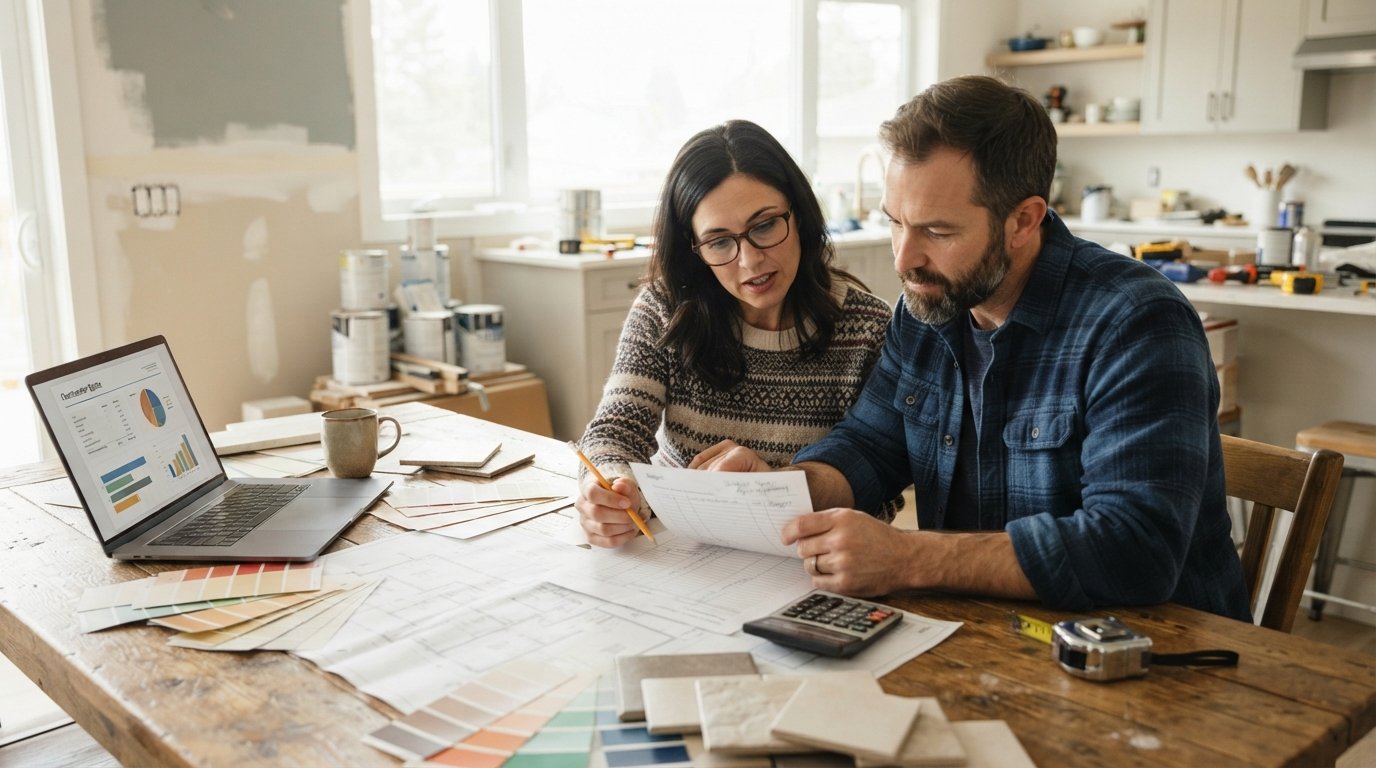
Your dream kitchen or spa bathroom can turn into a financial nightmare if you skip the planning stage. According to industry surveys, roughly half of all renovation projects exceed their initial budgets, and the gap is often tens of thousands of dollars. The homeowners who stay in control are not the ones with the biggest bank accounts. They are the ones who built a detailed, realistic budget before the first hammer swung. This guide walks you through how to budget for a home renovation step by step, from setting your total spending ceiling to tracking every invoice until the final walkthrough.
Step 1: Define the Project Scope Before You Talk Numbers
You cannot price a project you have not defined. Start by writing a one-page scope statement that lists exactly what you want to change and, just as important, what you are not changing. "Update the master bathroom" is too vague. "Replace the vanity, retile the shower, install a new toilet, and add a vent fan, keeping the existing layout and flooring" gives you something a contractor can actually quote.
Walk through your home room by room and separate your wish list into three buckets: must-haves, nice-to-haves, and future phases. Must-haves are the items that make the space functional and safe, such as fixing a leaking shower pan or upgrading outdated wiring. Nice-to-haves include heated floors or a freestanding tub. Future phases are projects you will tackle in a later year once you have rebuilt your savings.
This exercise matters because scope creep, not labor rates, is the number one budget killer. Every time you add a change order mid-project, you pay for the material, the extra labor, and often a markup for disrupting the schedule. A tight scope statement gives you a written reference point to say no, or at least to say "not this year."
Step 2: Research Realistic Costs for Your Area and Project Type
National averages are a starting point, but renovation costs swing wildly by region, home age, and material grade. A bathroom remodel that costs $18,000 in a mid-sized Midwest market can easily run $40,000 or more in a major coastal city. Before you set a single line item, gather at least three data points: national averages from reputable cost databases, local quotes from contractors, and recent project costs from neighbors or local real estate agents.
Break your research down by cost category so nothing hides in a lump sum:
- Materials: tile, fixtures, cabinets, countertops, paint, lumber, and hardware
- Labor: demolition, framing, plumbing, electrical, drywall, and finish work
- Permits and inspections: required for structural, electrical, plumbing, and sometimes cosmetic changes
- Design and engineering: architects, structural engineers, and interior designers
- Contingency: the cushion for surprises, which we will cover in detail below
If you want a shortcut to localized numbers and vetted professionals in one place, a platform like 180Remodel connects homeowners with contractors across services such as roofing, windows, bathroom remodeling, flooring, and painting, which makes early cost discovery far faster than cold-calling strangers. For a deeper framework on the planning side, our practical guide to budgeting a home renovation covers how to compare quotes and structure your spending plan.
Step 3: Set Your Total Budget and Your Hard Ceiling
Now it is time to decide what you can actually spend. There are two numbers you need: your target budget and your hard ceiling. The target budget is what you would like to spend. The hard ceiling is the absolute maximum you will allow, the number that forces you to pause the project and reassess if you approach it.
A common rule of thumb is to keep total renovation spending under 10 to 15 percent of your home's current value, though this varies by project type. Kitchen and bathroom remodels often recoup a large share of their cost at resale, while highly personalized additions may not. If you are financing the project, factor in loan interest, origination fees, and any impact on your monthly cash flow before you commit.
Then subtract your contingency fund immediately. Do not treat contingency as leftover money. Treat it as money that is already spent. A standard renovation contingency is 10 to 20 percent of the project cost, with the higher end reserved for older homes or projects that involve plumbing, electrical, or structural work behind the walls.
Step 4: Build a Line-Item Budget With a Contingency Buffer
A line-item budget turns your scope statement into a spreadsheet where every dollar has a job. Create columns for the item, estimated cost, actual cost, and variance. List every single component, even small ones like outlet covers, caulk, and dumpster rental, because small items add up fast across a whole-house project.
Here is a simple priority order for allocating funds when your estimates exceed your ceiling:
- Safety and code compliance first: electrical, plumbing, structural, and permits
- Functionality second: waterproofing, ventilation, insulation, and storage
- Aesthetics third: tile patterns, premium fixtures, and designer lighting
- Luxury last: smart home integration, custom millwork, and imported stone
When you trim, cut from the bottom of that list, never the top. A beautiful tile job over a failing shower pan is money wasted. Keep your contingency line separate from your construction lines so you are not tempted to spend it on an upgrade in week two.
Step 5: Get Multiple Quotes and Compare Apples to Apples
Three quotes is the minimum, and five is better for large projects. But the number of quotes matters less than how you compare them. Ask every contractor to bid from the same scope document and to break their price into labor, materials, permits, and allowances. An allowance is a placeholder amount for items you have not selected yet, such as tile or light fixtures. Low allowances are a classic way for a bid to look cheap while the final invoice balloons.
When you review bids, look for what is missing, not just what is included. Common omissions include debris removal, permit fees, painting after drywall repair, and final cleaning. Also check whether the contractor carries liability insurance and workers compensation, and whether they will pull permits in their name. Hiring an unlicensed contractor to save a few hundred dollars can void your homeowner insurance coverage if something goes wrong.
This is also the moment to negotiate, but negotiate scope, not just price. Ask what a bid would look like without a specific upgrade, or whether a different material at the same price point would be more durable. A contractor who is transparent about their numbers is usually a contractor who will be transparent about change orders.
Step 6: Plan Your Payment Schedule and Financing
Never pay the full project cost upfront. A standard payment schedule ties payments to milestones: a deposit of 10 to 30 percent at signing, then progress payments as demolition, rough-in, and finishes are completed, with a final payment of 5 to 10 percent held until the punch list is done and you have passed final inspection.
If you need financing, compare your options before you sign anything:
- Cash-out refinance: replaces your mortgage with a larger one, often at a lower rate but with closing costs
- Home equity loan or HELOC: a second lien with predictable or variable rates
- Personal loan: faster and unsecured, but usually a higher interest rate
- Contractor financing: convenient but often carries dealer fees baked into the price
- Credit cards: only for small projects you can pay off within a promotional window
Whatever route you choose, get preapproved before you sign a construction contract. Sellers and contractors take you more seriously when you can prove funds, and you avoid the disaster of a project stalling halfway through because financing fell apart.
Step 7: Track Spending and Manage Change Orders in Real Time
Your budget is a living document. Update your spreadsheet every time you pay an invoice or approve a change. Compare actual costs to estimates weekly, not monthly, so a small overrun does not quietly become a large one. If a line item goes over, find an offsetting saving elsewhere in the same category before you approve the next purchase.
Change orders deserve special attention. A change order is any alteration to the original scope, and it should be written, priced, and signed before the work happens. Verbal agreements lead to disputes. If your contractor says a change is "no big deal," ask for it in writing anyway. Most overruns trace back to a handful of unsigned change orders that each seemed minor at the time.
Finally, keep a running log of receipts, contracts, permits, and inspection reports. You will need them for warranty claims, insurance, and, if you sell, to show buyers that the work was done properly.
Common Budgeting Mistakes That Sink Renovations
Even careful homeowners trip over the same few traps. Watch for these patterns and correct them early. Skipping permits to save money can result in fines, forced removal of completed work, and disclosure problems at resale. Choosing the cheapest bid ignores the fact that the lowest price often reflects the thinnest scope. Designing as you go guarantees change orders, because every decision made after construction starts costs more than the same decision made during planning.
Another frequent error is underestimating the cost of living through a renovation. Temporary housing, eating out, and lost work time are real expenses. If your kitchen will be out of commission for six weeks, budget for meals and possibly a temporary refrigerator setup. And if you are managing the project yourself as an owner-builder, be honest about your time. Coordinating trades, ordering materials, and handling inspections is a part-time job, and mistakes there cost money.
Frequently Asked Questions
How much contingency should I add to a renovation budget?
Plan for 10 to 20 percent of the total project cost. Use 10 percent for cosmetic updates in newer homes and 20 percent or more for older homes or projects that open up walls, plumbing, or electrical systems. Treat contingency as spent money, not as a slush fund for upgrades.
Should I get a fixed-price bid or a cost-plus contract?
A fixed-price bid gives you cost certainty if your scope is fully defined. A cost-plus contract, where you pay actual costs plus a markup, can be fairer for projects with unknown conditions, but it shifts the risk of overruns to you. Ask for a detailed line-item breakdown either way.
What is the best way to pay for a home renovation?
Cash is cheapest because it avoids interest. If you must borrow, compare a cash-out refinance, home equity loan, HELOC, and personal loan against your timeline and rate. Get preapproved before signing a contract so the project never stalls for lack of funds.
Budgeting a renovation is not about predicting the future perfectly. It is about building a plan flexible enough to absorb surprises without derailing the project. Define your scope, research local costs, set a hard ceiling, hold a real contingency, collect comparable quotes, tie payments to milestones, and track every dollar until the punch list is signed. Do that, and you will finish with a home you love and a bank account that still works.
Learn more about Home Remodeling for guides, costs, and what to expect.
Compare Home Remodeling Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.