How to Budget for a Home Addition Project in 2026
Plan your home addition budget with confidence. Call 8337004293 for free quotes from local contractors and avoid surprise bills.
By Jackson Sawyer
Learn more about Home Remodeling for guides, costs, and what to expect.
Compare Home Remodeling Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.
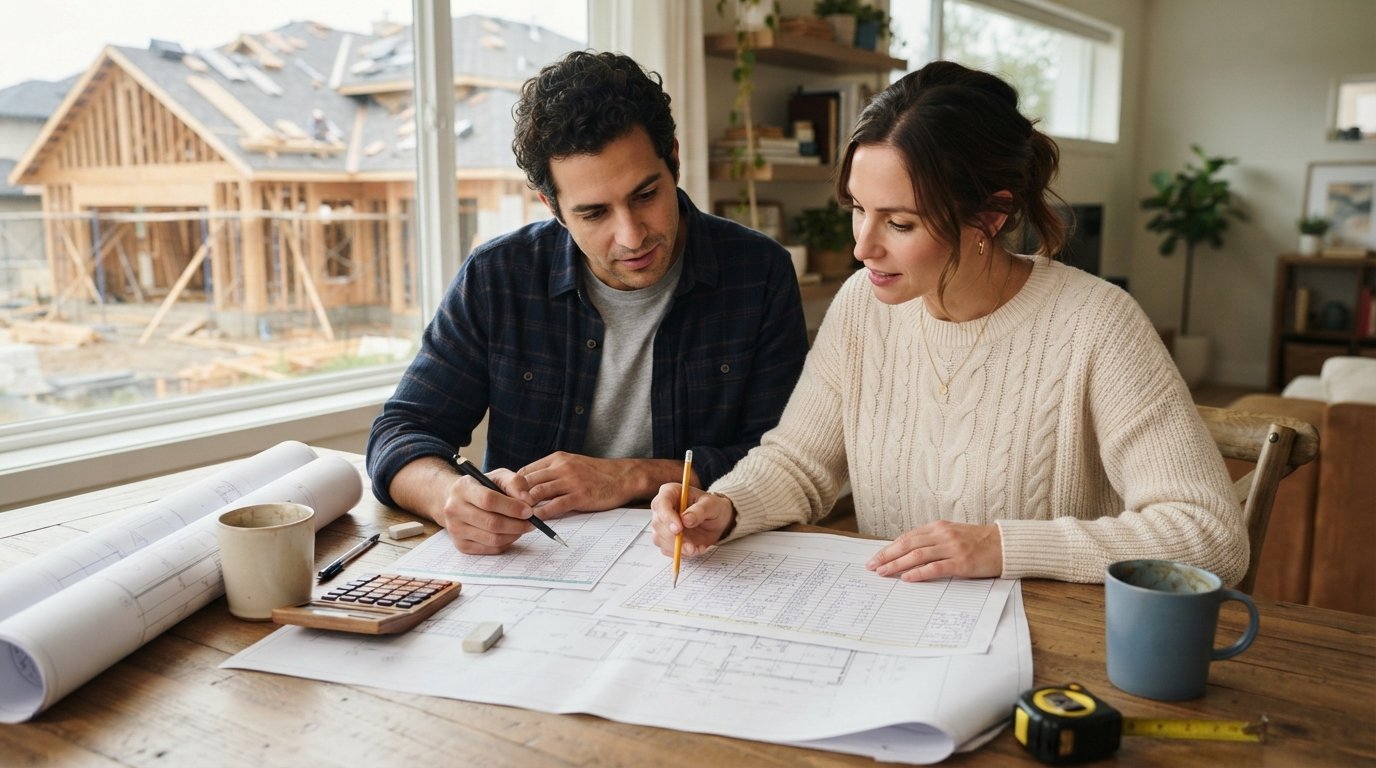
Planning a home addition is one of the most exciting and intimidating projects a homeowner can take on. Whether you need more space for a growing family, a dedicated home office, or a luxurious primary suite, the process promises lasting value and daily comfort. The harsh reality, however, is that additions routinely rank among the most expensive residential construction projects, and the gap between what homeowners expect to pay and what they actually spend can be enormous. Learning how to budget for a home addition project is not just about picking a number. It is about building a financial roadmap that protects you from surprises, keeps contractors honest, and ensures the finished space is worth every dollar.
At USremodel, we connect homeowners across the United States with independent local contractors who provide free, customized quotes for additions and remodels. That means you can compare multiple bids side by side and make a decision grounded in real market data rather than guesswork. Before you start collecting quotes, though, you need a solid budget framework in place. This guide walks you through every layer of that framework, from establishing a realistic total cost to setting aside the right contingency and choosing the best way to pay for the project.
Start With a Realistic Cost Range, Not a Wishful Number
The single biggest budgeting mistake homeowners make is anchoring to a number they heard from a neighbor or saw in a social media post. Construction costs vary dramatically based on region, labor availability, material selection, and the complexity of the addition itself. A 400 square foot bump-out in rural Texas will not cost the same as a 400 square foot second-story addition in suburban Seattle. Before you can budget intelligently, you need to understand the cost per square foot in your market and what that figure typically includes.
As a general starting point, basic room additions in most U.S. markets run between 200 and 400 dollars per square foot for standard finishes. High-end additions with custom cabinetry, premium flooring, and extensive structural work can easily exceed 500 dollars per square foot. A garage conversion or sunroom may fall below the low end, while a full primary suite with a bathroom and walk-in closet will push toward the upper range. These numbers are not quotes. They are guardrails that help you screen contractor bids and spot outliers.
To narrow the range for your specific project, gather at least three detailed estimates. USremodel makes this process simple by matching you with local contractors who specialize in additions and providing you with multiple customized quotes at no cost. When you compare those bids, look beyond the bottom line. Ask each contractor to break down labor, materials, permits, and allowances so you can see exactly where the money is going.
Break the Budget Into Hard and Soft Costs
A complete home addition budget has two major categories: hard costs and soft costs. Hard costs cover the physical construction, including framing, foundation, roofing, electrical, plumbing, HVAC, drywall, flooring, paint, and fixtures. Soft costs cover everything else required to get the project from concept to completion, such as architectural drawings, engineering reports, permit fees, inspections, and project management. Homeowners frequently underestimate soft costs, which can add 15 to 25 percent to the total project price.
Within those two categories, it helps to itemize further so nothing slips through the cracks. A typical addition budget includes:
- Design and engineering fees (architect, structural engineer, surveyor)
- Permits, inspections, and impact fees from your local municipality
- Site preparation, excavation, and foundation work
- Framing, roofing, siding, windows, and exterior finishes
- Electrical, plumbing, and HVAC rough-in and final connections
- Insulation, drywall, interior trim, paint, flooring, and fixtures
- Contingency reserve and final cleanup or landscaping restoration
Once you have a line-item breakdown, assign a dollar figure to each category based on your contractor bids and local material prices. This exercise forces you to confront the true scope of the project and reveals which areas offer the most opportunity for savings. For example, choosing standard window sizes instead of custom dimensions can reduce both material and labor costs without sacrificing much visual appeal.
Set a Contingency Fund That Actually Protects You
No matter how carefully you plan, home additions encounter surprises. Hidden water damage, outdated wiring, unstable soil, or a sudden spike in lumber prices can derail even the most meticulous budget. That is why every addition budget must include a contingency reserve. Industry professionals typically recommend setting aside 10 to 20 percent of the total project cost for unexpected expenses. For older homes or projects involving structural changes, lean toward the higher end.
A contingency fund is not padding for upgrades or last-minute design changes. It is insurance against the unknown. If you spend it, you need to adjust your scope or find savings elsewhere. If you do not spend it, you can apply the remaining balance to finishes or keep it as a cushion for future maintenance. Treating the contingency as untouchable until a genuine surprise arises is the discipline that separates a smooth project from a financial crisis.
It also helps to decide in advance how you will handle change orders. Contractors issue change orders when the scope of work shifts after construction begins. Each change order carries a cost, and those costs add up quickly. Establish a rule with your contractor that any change order above a certain dollar amount requires written approval and a revised timeline before work proceeds. This simple practice keeps you in control of the budget rather than reacting to invoices after the fact.
Choose the Right Financing Strategy Before You Break Ground
How you pay for the addition matters as much as how much you spend. Paying entirely in cash avoids interest charges and keeps the project debt-free, but few homeowners have the full amount liquid. For everyone else, the right financing tool depends on how much equity you have, your credit profile, and how long you plan to stay in the home.
Common options include a home equity line of credit (HELOC), a home equity loan, a cash-out refinance, a construction loan, or a personal loan. A HELOC offers flexibility because you draw funds as needed, which pairs well with the phased payment schedule of a construction project. A home equity loan provides a fixed rate and predictable monthly payments, which simplifies long-term budgeting. A cash-out refinance replaces your existing mortgage with a larger one and gives you the difference in cash, often at a lower interest rate than other options. Construction loans are designed specifically for building projects and convert to permanent mortgages once the work is complete.
Before committing to any financing product, calculate the total cost of borrowing, including closing costs, origination fees, and interest over the life of the loan. Compare that figure against the expected value the addition will add to your home. If the numbers do not justify the expense, consider scaling back the project or postponing it until you have more equity or savings. You can also explore how home additions increase value to better understand the return on investment for different types of projects.
Get Multiple Quotes and Compare Them Carefully
Collecting multiple quotes is not just a price-shopping exercise. It is a risk-management strategy. Contractors who know they are competing for your project are more likely to provide detailed, transparent estimates. They are also more likely to flag potential issues early rather than discovering them mid-construction when costs are harder to control.
When you receive quotes, compare them line by line. Look for allowances for fixtures and finishes, because a low allowance can make a bid appear cheaper while leaving you responsible for overages later. Check whether permits and inspections are included. Confirm the payment schedule and make sure it is tied to completed milestones rather than arbitrary dates. Ask about warranties, insurance, and how the contractor handles subcontractors. A bid that is thousands of dollars lower than the others is not automatically the best deal. It may indicate omitted scope, inferior materials, or a contractor who plans to make up the difference through change orders.
If you want to simplify the process of finding and vetting contractors, 180 Remodel connects homeowners with professional contractors for a wide range of home improvement services, from roofing and windows to bathroom remodeling and flooring. Using a platform that pre-screens contractors saves time and reduces the risk of hiring an unqualified builder.
Control Costs During Construction
Even the best budget requires active management once construction begins. Stay involved without micromanaging. Attend regular check-ins with your contractor, review progress against the schedule, and track expenses against your line-item budget. If you notice spending trending above plan in one category, address it immediately rather than waiting until the project is finished.
One of the most effective cost-control tactics is to make decisions early. Delays caused by indecision about tile, paint colors, or fixture models can push the project into a more expensive season or force rushed purchases at premium prices. Create a decision calendar with your contractor that lists every selection deadline. Meeting those deadlines keeps the project moving and prevents costly work stoppages.
Another tactic is to handle certain non-structural tasks yourself if you have the skills and time. Painting, landscaping, and final cleaning are common DIY candidates that can reduce labor costs without compromising the structural integrity of the addition. However, be honest about your limitations. Electrical, plumbing, and HVAC work should always be left to licensed professionals for safety and code compliance.
Plan for the Hidden Costs Nobody Talks About
Beyond the obvious construction expenses, home additions carry a set of hidden costs that can catch homeowners off guard. Property taxes often increase after an addition because the assessed value of the home rises. Homeowners insurance premiums may also go up to reflect the higher replacement cost. If your addition includes a bathroom or kitchen, your utility bills will likely increase as well. These ongoing costs do not appear in the construction contract, but they affect your long-term financial picture.
There are also temporary costs to consider. You may need to move furniture, store belongings, or relocate your family during the noisiest phases of construction. If the addition blocks access to part of your home, you might need to arrange alternative living arrangements for a few weeks. Budgeting a small amount for these disruptions prevents them from becoming financial emergencies.
Finally, think about resale. Not every addition recoups its full cost when you sell. According to national remodeling data, minor kitchen remodels and bathroom additions tend to recover a higher percentage of their cost than elaborate sunrooms or garage conversions. If your primary goal is to increase home value, choose a project that aligns with what buyers in your neighborhood expect. If your goal is personal enjoyment, that is a valid reason too, but go into the project with clear eyes about the financial trade-off.
Budgeting for a home addition is a skill that combines research, discipline, and honest self-assessment. Start with realistic cost ranges, separate hard costs from soft costs, build a contingency fund, choose financing that fits your situation, and manage the budget actively from the first day of construction to the last. When you approach the project with a detailed plan and multiple contractor quotes in hand, you transform a stressful gamble into a confident investment in your home.
Learn more about Home Remodeling for guides, costs, and what to expect.
Compare Home Remodeling Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.